What should I know about appraisals in Grand Rapids?
When you’re buying a home in Grand Rapids, the appraisal is a crucial step that can directly impact whether your deal moves forward, if you need to renegotiate, or even if your financing falls through. Most buyers hear about appraisals from their lender, but few understand how this process works locally—or what to do if the appraised value doesn’t match the agreed purchase price.
Quick Answer
An appraisal in Grand Rapids is a third-party opinion of your future home’s value, required by most lenders before closing. If the appraised value comes in lower than your agreed price, your lender won’t finance the difference, which can mean coming up with more cash or renegotiating with the seller.
Appraisals are common here, especially on financed purchases, and can be unpredictable even in a hot market. I help buyers plan for appraisal risk up front, so you’re not caught off guard if the value comes in short. If you’re dealing with this situation, I’m happy to walk through it with you.
How Grand Rapids Appraisals Actually Work
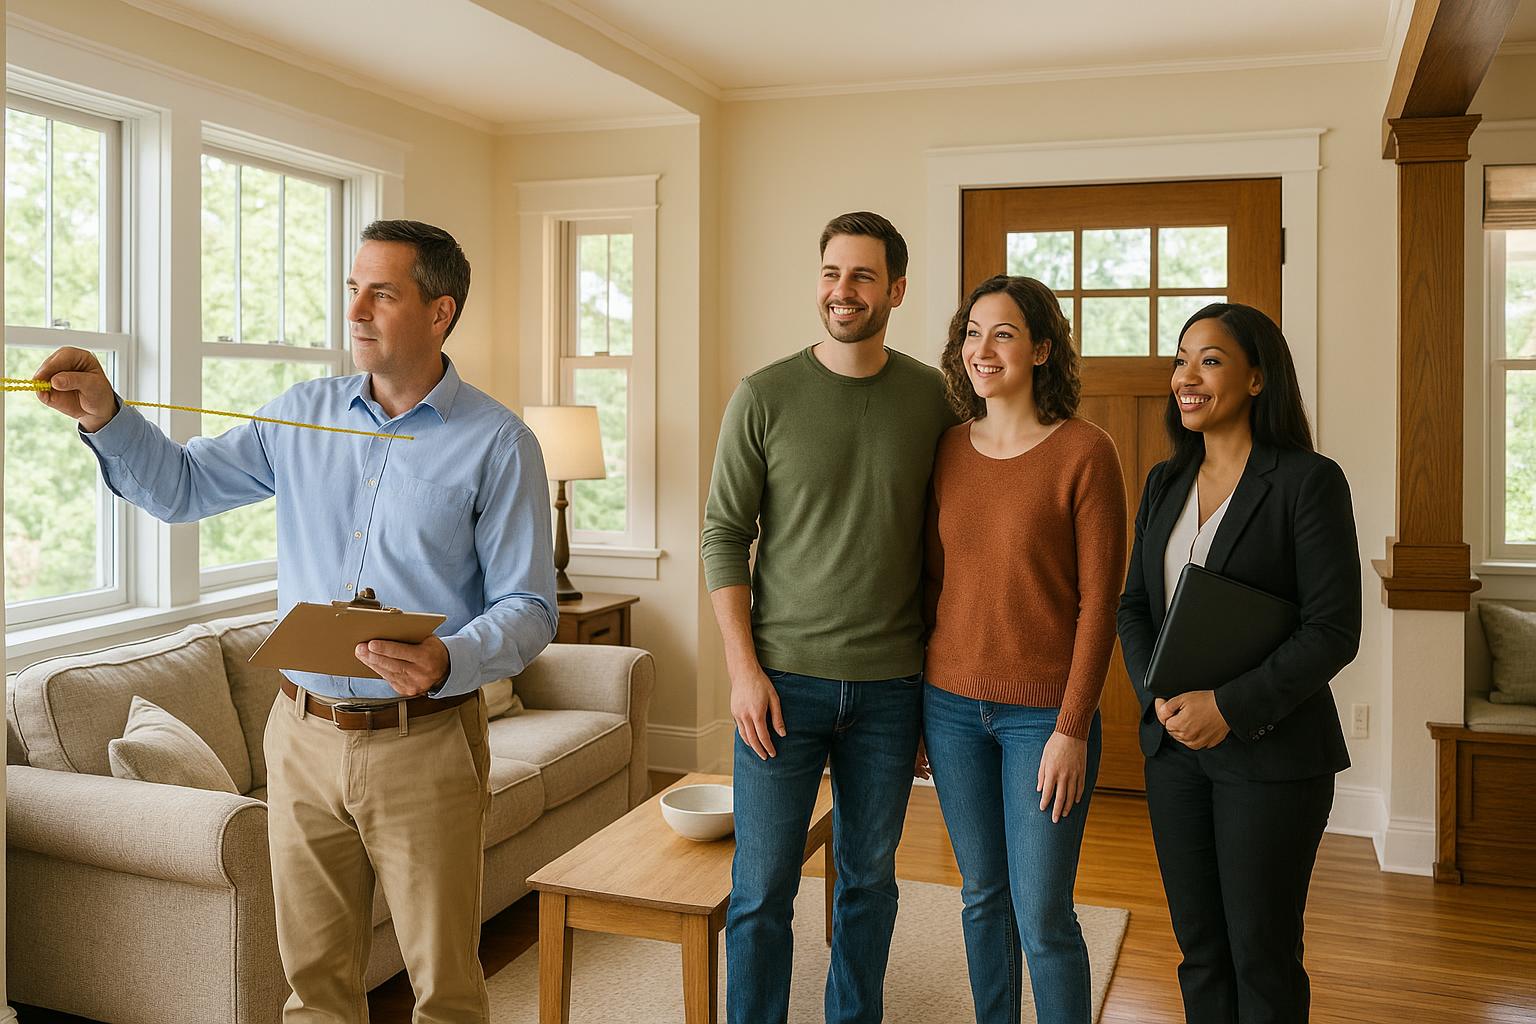
In Grand Rapids, once your offer is accepted and you’ve completed inspections, your lender will order an appraisal from a licensed professional. The appraiser visits the property, reviews recent comparable sales, and submits a report estimating the home’s value. This report is required for nearly all financed purchases, whether conventional, FHA, VA, or rural development loans. The process typically takes 5–10 days after it’s ordered.
The appraisal is not the same as a home inspection. It focuses on value, not the home’s condition—though the appraiser will note obvious safety issues or code violations, especially for FHA or VA loans. If the appraised value meets or exceeds your purchase price, you move forward as planned. If it comes in low, your lender will base your loan on the lower value, not your offer.
Strategy 1: Protecting Your Earnest Money and Offer Terms
If the appraisal is lower than the agreed price, buyers can be at risk of losing their earnest money deposit if they can’t close. In Grand Rapids, most purchase agreements include an appraisal contingency. This protects your deposit if you need to back out or renegotiate due to a low appraisal. Always confirm this clause is included and clearly written in your offer—especially if you’re competing in a multiple-offer situation, where some buyers may waive it to appear stronger.
Jason’s take: In the current Grand Rapids market, I rarely recommend waiving your appraisal contingency unless you have enough cash to cover a potential shortfall. Most buyers do not, and it’s not worth risking your deposit unless you’re fully prepared.
Strategy 2: Understanding Appraisal Gaps and Bridge Strategies
When homes sell above asking in Grand Rapids—especially in popular neighborhoods like Eastown, Alger Heights, or Forest Hills—buyers sometimes include an “appraisal gap guarantee.” This means you agree up front to bring extra cash to closing if the appraisal is low, up to a set amount. For example, if you offer $320,000 on a home and it appraises at $310,000, and you’ve written a $5,000 gap guarantee, you’re agreeing to cover the difference.
This strategy can make your offer more competitive, but you must be clear on how much cash you’re comfortable bringing. Review your loan approval, savings, and talk to your lender about what this means for your monthly payment and closing costs. The CFPB explains appraisal basics here and why your lender cares about them.
Strategy 3: What to Do If the Appraisal Comes In Low
If you get a low appraisal, you generally have three options: (1) negotiate with the seller to lower the price, (2) bring extra cash to closing to cover the gap, or (3) dispute the appraisal if you believe there are factual errors or missed comps. In Grand Rapids, sellers will sometimes reduce the price—especially if there aren’t backup offers or the property has been on the market a while.
Jason’s take: I’ve seen sellers hold firm in ultra-competitive price ranges, but in most cases, we can negotiate a middle ground. I always review the appraisal report with buyers to spot errors or missing data before accepting the value at face value.
Strategy 4: Using Local Market Data to Prepare Your Offer
A practical rule of thumb: If you’re bidding significantly over the asking price, ask your agent to pull recent closed sales within a quarter mile and within the last 90 days. Appraisers are required to use the most recent and similar comparables available, per Fannie Mae guidelines. If no sales support your offer price, assume you may face an appraisal gap and plan accordingly.
This is especially important in fast-appreciating Grand Rapids neighborhoods, where closed sales may lag behind current list prices. Ask for a side-by-side of current pending and recently closed comps before making a strong over-ask offer.
Real Buyer Case Study
Last year, I worked with buyers on a $295,000 home in the popular Alger Heights area. We competed with three other offers and included a $5,000 appraisal gap guarantee in our offer. The appraisal came in $7,000 under the purchase price. We reviewed the report and found one comp that was missing—a similar home nearby that had closed just a week prior. We submitted a reconsideration request to the lender with the new data. The appraiser updated the report, and the value came up to our contract price. The deal closed on time, and my buyers didn’t have to bring extra cash.
Grand Rapids Buyer Market Insight
In Grand Rapids, buyer competition is strongest in the $250,000–$400,000 range, especially in top-rated school districts. Multiple offers are common, and appraisals sometimes lag behind rising list prices. I see more buyers including appraisal gap coverage in Forest Hills and East Grand Rapids, while in outlying areas or higher price points, sellers are often more flexible if an appraisal comes in low. Knowing your price range and neighborhood demand helps you plan for appraisal risk up front.
Frequently Asked Questions About Buying in Grand Rapids
What happens if the appraisal comes in lower than my offer?
Your lender will only finance up to the appraised value. You’ll need to renegotiate, bring extra cash, or potentially back out if you can’t bridge the gap.
Do I get a copy of the appraisal report?
Yes. Federal law requires your lender to provide you with a copy of the appraisal report once it’s completed—usually within a few days of the appraiser’s visit.
Can I appeal a low appraisal?
Yes, you can ask your lender to request a reconsideration of value if you find factual errors or stronger comparable sales. Success is not guaranteed, but it’s worth trying.
Is the appraisal the same as an inspection?
No. The appraisal is for your lender’s benefit and focuses on value, not a full assessment of the home’s condition. You should still get a separate home inspection.
Related Grand Rapids Buyer Resources
- What should I know about seller concessions in Grand Rapids?
- Should I get a sewer line inspection when buying in Grand Rapids?
- Bloomberg: Grand Rapids first-time home buyers
About the Author
Jason Pohlonski
is a Michigan licensed real estate salesperson with Keller Williams Grand Rapids East. He helps buyers and sellers throughout Grand Rapids, East Grand Rapids, Forest Hills, Ada, Byron Center, Jenison, Cascade, and surrounding West Michigan communities.
Jason began his real estate career in Chicago in 2004, later expanding his experience in Ann Arbor from 2014 to 2019, and has been serving clients in the Grand Rapids area since 2019.
With over 20 years of combined real estate experience across multiple markets, Jason focuses on helping clients make clear real estate decisions involving pricing, offer terms, inspections, appraisals, relocation timing, and buy-sell planning.
Industry Recognition
Jason is recognized by platforms and industry organizations including Zillow, Grand Rapids Magazine Real Estate All-Stars, and Real Producers for his work serving West Michigan buyers and sellers.
Jason also supports One More Moment, a nonprofit that grants wishes to late-stage cancer patients, by donating $100 for every successful closing.
Professional Disclosure
Jason Pohlonski
Michigan Licensed Real Estate Salesperson
License Verification: Verify Michigan License #6501386166
Brokerage: Keller Williams Grand Rapids East
Brokerage Office: 1555 Arboretum Dr. SE, Grand Rapids, MI 49546
📱 Call or text: 616-916-9770
📅 Schedule consultation:
https://calendly.com/pohlonskirealestate/30min
📧 Email: jpohlonski@kw.com
This article reflects real client experiences and market conditions in Grand Rapids and surrounding communities at the time of publication. Real estate outcomes can vary depending on market conditions, property characteristics, buyer demand, financing terms, inspection results, appraisal results, and lender requirements.
This article is for general informational purposes only and is not legal, tax, financial, insurance, engineering, inspection, or floodplain determination advice. Buyers and sellers should consult qualified professionals before making decisions involving financing, insurance, inspections, taxes, legal issues, or property risk.