Is a Cash Offer Really Better Than a Financed Offer in Forest Hills?
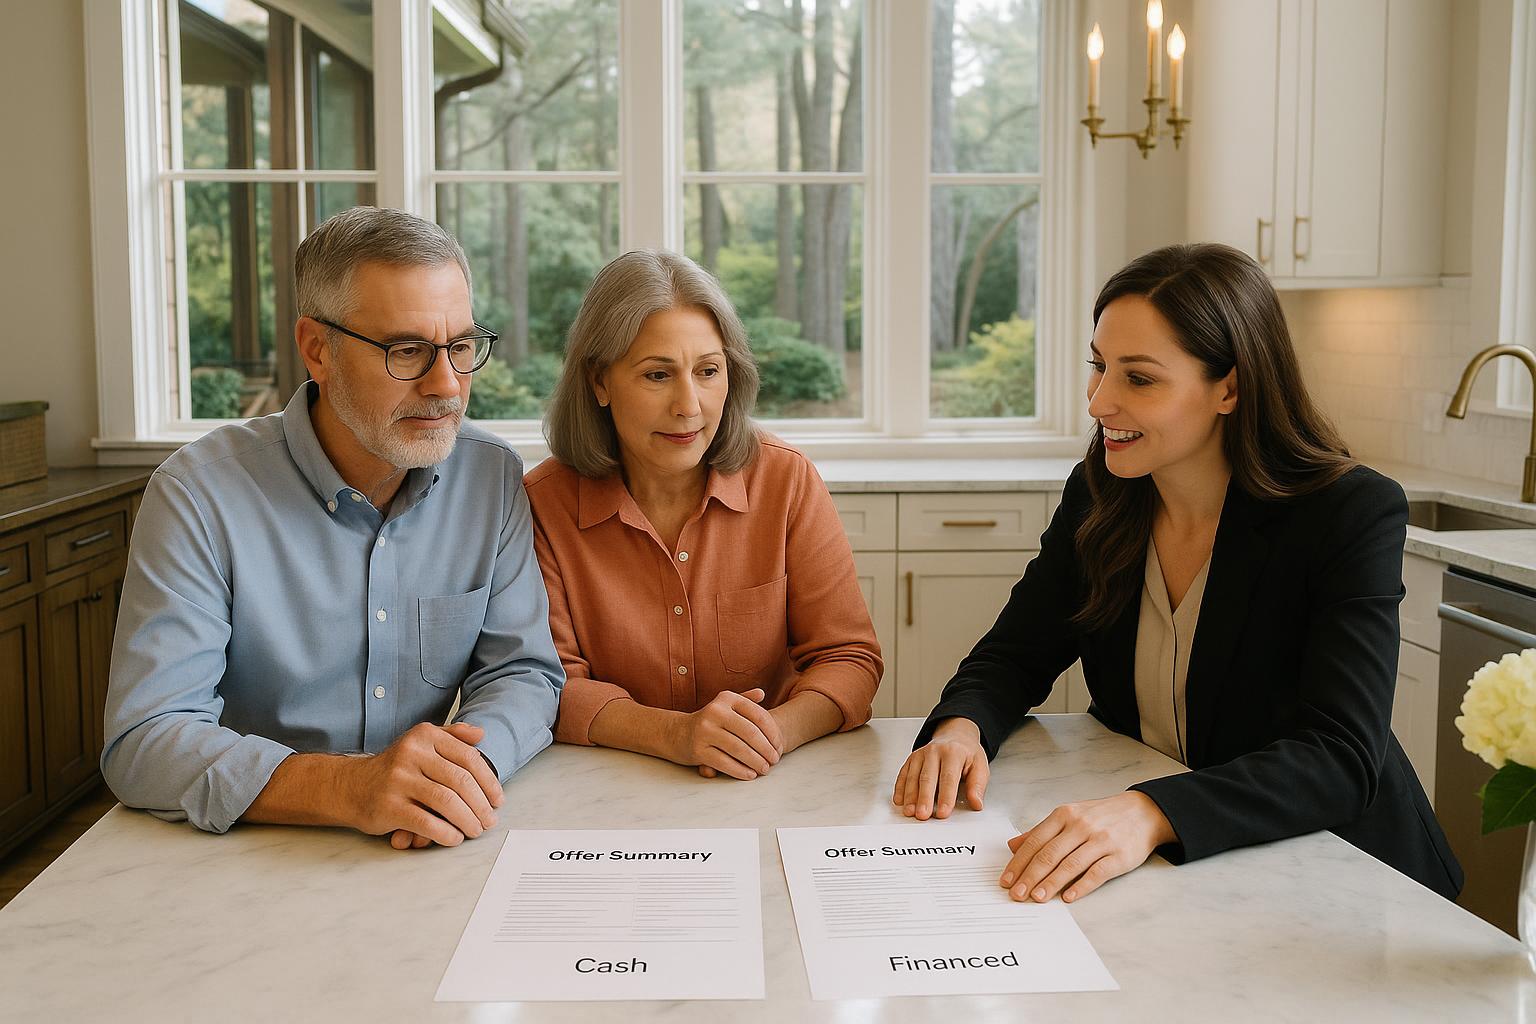
When you receive multiple offers on your Forest Hills home, the decision isn’t always as simple as “cash is king.” The strongest offer isn’t just about the amount—Forest Hills sellers need to weigh the reliability of the buyer, the likelihood of a smooth closing, and what actually ends up in your pocket at the end of the transaction. Here’s how to break down the real-world pros and cons of cash vs. financed offers in our local market—so you can choose with confidence, not just hope for the best.
Quick Answer
In Forest Hills, a cash offer is often less risky and more likely to close on time, but a financed offer can sometimes deliver a higher net price—especially in competitive price ranges near Forest Hills Central and Ada. The best choice comes down to risk tolerance, your timeline, and the specific terms each buyer offers.
1. Closing Certainty: How Much Risk Are You Willing to Accept?
Cash offers in Forest Hills nearly always come with fewer contingencies and a lower chance of the sale falling apart before closing. With a cash buyer, you skip the lender’s appraisal requirement and most financing-related delays. This is especially valuable if you’re buying another home or coordinating a move—every day of uncertainty can add stress and cost. In the $600K–$1M range, I’ve seen cash offers close in as little as ten days, while financed offers often need 30–45 days.
However, not every financed offer is risky. When a buyer is putting down 20% or more, is pre-approved with a reputable Grand Rapids lender, and waives some contingencies, the risk of a delayed or failed closing drops sharply. Still, the reality is that in Forest Hills, roughly 1 in 8 financed deals experience at least one significant delay due to lender, appraisal, or underwriting issues (NAR research backs this up nationally, and my local experience reflects it).
2. Net Proceeds: Don’t Let Offer Price Fool You
Forest Hills sellers often get excited by a higher financed offer—especially if it’s $10K–$20K above the best cash bid. But the final number you put in your pocket can change fast. If a financed buyer’s lender-ordered appraisal comes in low, you may have to renegotiate, reduce your price, or risk the deal falling apart. With a cash offer, the buyer can choose to waive the appraisal altogether, and even if they don’t, a cash buyer isn’t constrained by lender limits.
A practical rule of thumb: in Forest Hills, if the cash offer is within 1–2% of the financed offer and both are clean (minimal contingencies, reasonable inspection terms), most sellers opt for cash to avoid headaches. But if the financed offer is significantly higher and the buyer has a strong local lender, it’s worth serious consideration—especially for homes near Forest Hills Central High School or in Ada Village where buyer demand can push financed offers higher than cash.
3. Timeline and Flexibility: How Fast Do You Need to Close?
One of the biggest advantages of a cash offer is speed. Forest Hills cash buyers are often flexible with your preferred closing and possession dates. If you need to sell quickly—maybe you’re relocating for a job, or you already have a new home under contract in Cascade Township—a cash buyer is less likely to cause last-minute delays. This is particularly true for homes in Cascade, where many buyers are moving in from out of state and want to close before the new school year.
Financed buyers, on the other hand, have to work around lender schedules, appraisals, and underwriting. Even a smooth loan process can hit snags: document requests, last-minute verifications, or appraisal backlogs can all push your closing date back by a week or more. If your move-out timing is tight, or you’re trying to coordinate with school calendars or a double-move, a cash offer can reduce your stress and risk.
4. Contingencies and Buyer Strength: What’s Actually in the Offer?
It’s easy to focus on “cash vs. financed,” but the fine print matters just as much. In Forest Hills, financed buyers sometimes offer to waive the appraisal gap (agreeing to bring extra cash if the appraisal is low) or shorten inspection periods to compete with cash. Look for offers with fewer contingencies, strong earnest money deposits, and pre-approval letters from respected local lenders like Lake Michigan Credit Union or Treadstone Funding. These details matter more than the financing type alone.
In neighborhoods near Forest Hills Eastern High School, it’s not uncommon to see strong financed offers with minimal contingencies outcompete cash offers that come in low or ask for major inspection concessions. Review each offer’s terms line by line—don’t assume cash always means “best.”
Real Seller Case Study: Ada Village, $825K Range
Recently, I listed a custom home in Ada Village in the $825,000 range. We received two offers: one all-cash at list price, and one financed offer at $15,000 over list. The financed buyer was putting 25% down and provided a local lender pre-approval with waived appraisal gap coverage. After reviewing the terms, my seller chose the financed offer because the buyer’s agent had a strong reputation, the lender was responsive, and the buyer agreed to a non-refundable deposit after inspection. The deal closed in 32 days—on time and at the higher price. In this case, the seller’s risk was low and the extra $15,000 netted was well worth it.
Forest Hills Market Insight
One trend I’m seeing in Forest Hills is that homes near Forest Hills Central High School and newer construction in Cascade Township consistently attract more cash buyers—often relocation executives or buyers coming from higher-priced metro areas. In contrast, older homes or those closer to Forest Hills Northern tend to draw more financed buyers, especially families moving within the district. This pattern impacts not just how offers are structured, but also how aggressive buyers get with contingencies and timelines.
Frequently Asked Questions About Selling in Forest Hills School District
- How often do cash offers beat financed offers in Forest Hills?
Cash offers win about 40% of the time when they’re close in price or terms, but strong financed offers with waived contingencies can absolutely compete—especially in popular neighborhoods. - Can I negotiate with both cash and financed buyers at once?
Yes. Many Forest Hills sellers counter both buyers to improve terms. It’s common to ask a cash buyer to match a financed offer or request the financed buyer to waive certain contingencies. - What if the financed offer’s appraisal comes in low?
You’ll need to renegotiate. Some buyers will cover the gap; others may walk away. That’s why appraisal gap coverage is crucial in competitive Forest Hills deals. - Is a quick closing always better?
Not always. If you need extra time to move, negotiate a post-closing possession. Cash buyers tend to be more flexible, but some financed buyers will accommodate your needs as well.
Related Forest Hills Seller Resources
- How to Price a Unique Forest Hills Home With Few Comparable Sales
- How Do I Handle Showings for My Grand Rapids Home if I Have a Busy Schedule?
- How Do I Decide Between a Condo or House in Grand Rapids?
About the Author
Jason Pohlonski
is a Michigan licensed real estate salesperson with Keller Williams Grand Rapids East. He helps buyers and sellers throughout East Grand Rapids, Grand Rapids, Forest Hills, Ada, Byron Center, Jenison, Cascade, and surrounding West Michigan communities.
Jason began his real estate career in Chicago in 2004, later expanding his experience in Ann Arbor from 2014 to 2019, and has been serving clients in the Grand Rapids area since 2019.
With over 20 years of combined real estate experience across multiple markets, Jason focuses on helping clients make clear real estate decisions involving pricing, offer terms, inspections, appraisals, relocation timing, and buy-sell planning.
Industry Recognition
Jason is recognized by platforms and industry organizations including Zillow, Grand Rapids Magazine Real Estate All-Stars, and Real Producers for his work serving West Michigan buyers and sellers.
Jason also supports One More Moment, a nonprofit that grants wishes to late-stage cancer patients, by donating $100 for every successful closing.
Professional Disclosure
Jason Pohlonski
Michigan Licensed Real Estate Salesperson
License Verification: Verify Michigan License #6501386166
Brokerage: Keller Williams Grand Rapids East
Brokerage Office: 1555 Arboretum Dr. SE
Grand Rapids, MI 49546
📱 Call or text: 616-916-9770
📅 Schedule consultation:
https://calendly.com/pohlonskirealestate/30min
📧 Email: jpohlonski@kw.com
This article reflects real client experiences and market conditions in East Grand Rapids, Grand Rapids, and surrounding West Michigan communities at the time of publication. Real estate outcomes can vary depending on market conditions, property characteristics, buyer demand, financing terms, inspection results, appraisal results, and lender requirements.
This article is for general informational purposes only and is not legal, tax, financial, insurance, engineering, inspection, or appraisal advice. Buyers and sellers should consult qualified professionals before making decisions involving financing, insurance, inspections, taxes, legal issues, property risk, or valuation.