How to Decide If a Cash Offer Is Best for Your Forest Hills Home
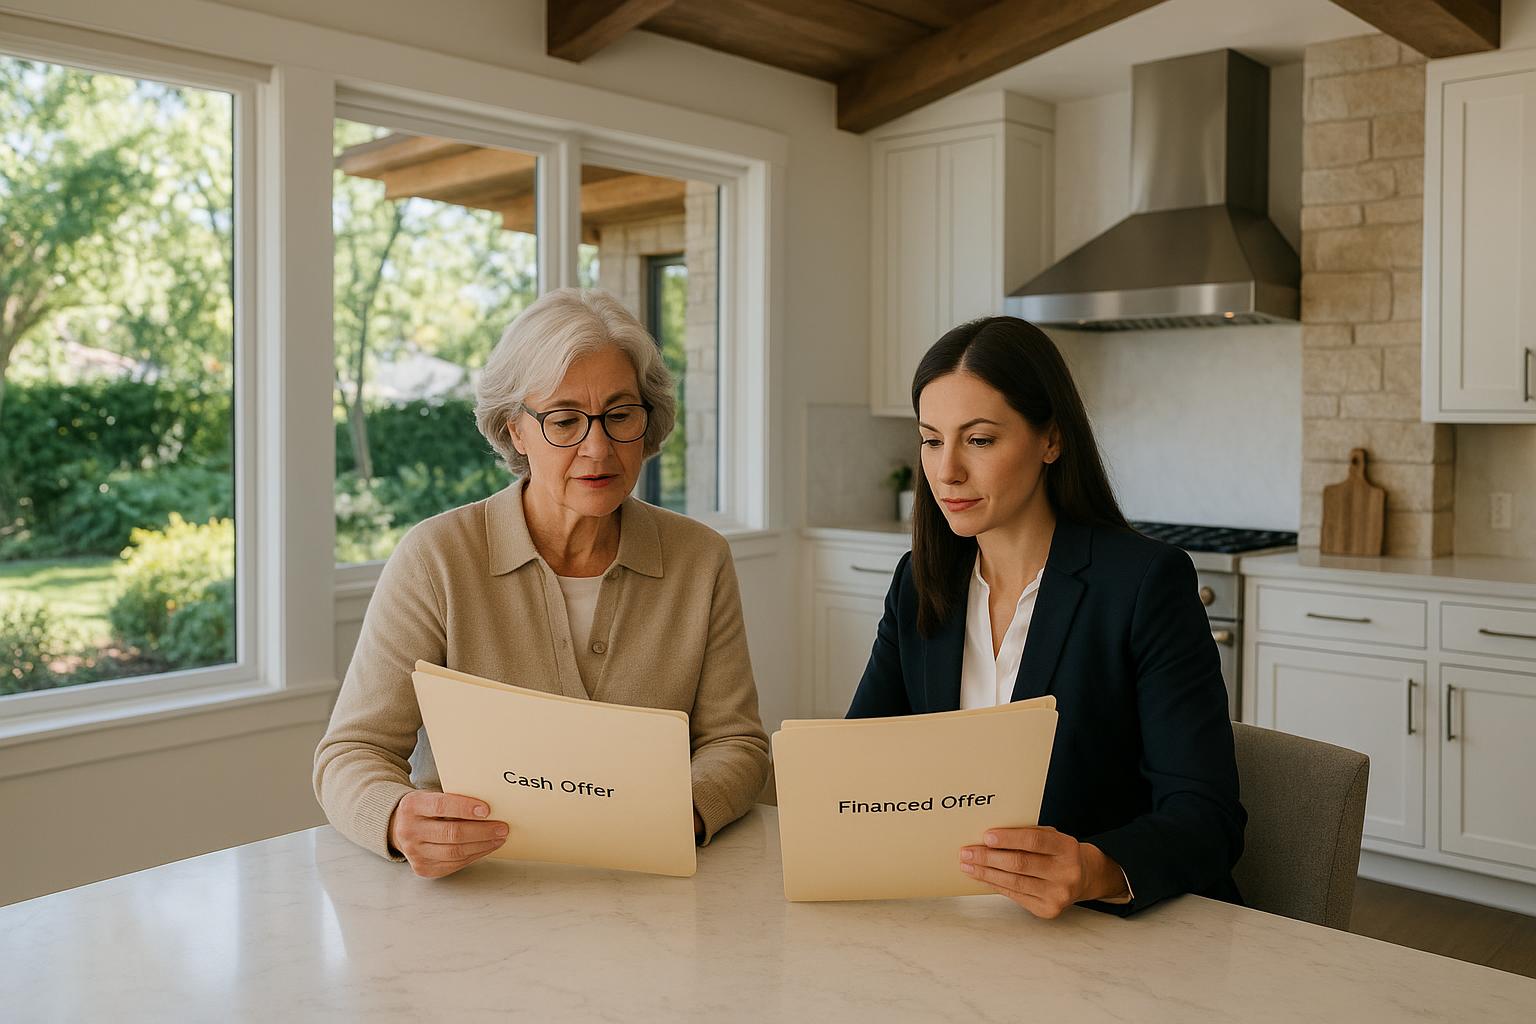
If you’re selling your home in the Forest Hills School District and receive a cash offer, your first question should be: “Is this really my best option, or could a financed offer net me more?” The key strategy for Forest Hills sellers is to compare not just the offer price, but the total risk, speed, and certainty each offer provides—especially in a market where $400K–$1.5M homes attract both relocation buyers and local move-up families. Let’s break down exactly how to weigh a cash offer versus a financed offer for your Forest Hills home.
Quick Answer
In Forest Hills, a cash offer often means a faster, more predictable closing and fewer hurdles—but may come at a lower price than a strong financed offer. To decide what’s best, carefully compare net proceeds, closing certainty, inspection terms, and the true timeline based on your needs.
1. Weighing Net Proceeds—Not Just Offer Price
The headline cash offer number is only part of the equation. What really matters is your net proceeds after closing costs, any seller-paid concessions, and potential repairs. In the Forest Hills market, cash buyers often expect a discount—sometimes 3–7% below what a top financed buyer might pay—because they’re offering speed and certainty. However, if a financed offer is contingent on a high appraisal or asks for costly repairs, your net could end up being lower than expected.
Ask your agent to run a side-by-side seller net sheet for each offer. For example, a $700,000 cash offer with no inspection and a two-week close might net more than a $720,000 financed offer that requires $15,000 in repairs and comes with appraisal risk. Always look beyond the top-line number to the details that affect your bottom line.
2. Understanding Risk: Appraisals, Financing, and Inspections
Cash offers remove two major risks: appraisal and financing approval. In Forest Hills—especially for homes zoned to Forest Hills Central High School or in Cascade Township—many buyers use conventional loans, but every financed offer is subject to lender approval and a satisfactory appraisal. Appraisal shortfalls can be a real issue, especially if the home is priced aggressively or has unique features not reflected in recent sales.
Cash buyers may also waive inspections or limit requests, letting you skip last-minute negotiations. On the other hand, some financed buyers in Forest Hills, particularly relocation buyers, may insist on full inspections and repair credits, which can delay or derail a deal. Be sure to factor in the risk of an offer falling through when making your decision.
3. Timeline and Flexibility: Matching Your Moving Plans
One of the biggest advantages of a cash offer is speed. In Forest Hills, cash buyers can close in as little as 7–14 days, while financed offers typically take 30–45 days, depending on the lender and appraisal schedule. If you’re buying your next home in Ada Village or need a quick move for a job relocation, a cash offer’s certainty and flexible timeline can be worth thousands in reduced stress and carrying costs.
Ask each buyer about their flexibility on possession after closing—many Forest Hills cash buyers are local investors or downsizers who can offer post-closing occupancy, giving you time to move. By contrast, some financed buyers (especially those moving for Forest Hills Northern High School enrollment) may need immediate occupancy, limiting your options.
4. Decision Framework: When Does a Cash Offer Win?
Here’s a practical rule of thumb for Forest Hills sellers: If the cash offer is within 2–3% of the highest financed offer, and the financed offer has high appraisal or inspection risk, the cash offer is usually the safer and smarter choice. If the gap is larger, consider your risk tolerance, timeline, and whether you have a backup plan if the financed deal falls apart.
Use the following framework:
- If you need a fast, guaranteed close and minimal hassle, lean toward cash.
- If you’re comfortable waiting and have strong offers with appraisal guarantees or waived contingencies, a financed offer may yield more money.
- If your home is unique or hard to appraise—such as a custom home on a wooded lot in Ada—cash can help avoid low appraisal surprises.
Reviewing local market data from sources like Greater Regional Alliance of Realtors can help you see how cash vs. financed deals have played out in recent Forest Hills sales.
Real Seller Case Study
Last year, I listed a $950,000 home in Cascade Township, walking distance to Forest Hills Central High School. We received three offers: one cash at $925,000 with no contingencies, and two financed at $950,000 and $960,000. The highest offer was from a family relocating for Forest Hills Northern High School and required appraisal and inspection contingencies. After reviewing net proceeds and risk, my sellers chose the $925,000 cash offer. The cash buyer closed in 10 days, allowed my clients to stay an extra week post-closing, and there were no repair requests. The financed offers both included appraisal gaps, but the sellers valued certainty and timing for their own move to Ada. The outcome: a smooth, drama-free sale and a stress-free transition to their new home.
Forest Hills Market Insight
One trend I’ve seen recently: homes with larger wooded lots in Ada and Cascade Township often attract more cash buyers, especially those seeking privacy or planning renovations. Meanwhile, homes zoned to Forest Hills Eastern High School tend to draw more financed buyers relocating for schools, sometimes pushing prices higher but also introducing more appraisal and inspection complexity. Understanding which buyer pool your home attracts can help you anticipate the types of offers you’ll see and what terms are most valuable in your situation.
Frequently Asked Questions About Selling in Forest Hills School District
- Do cash offers always close faster than financed offers?
Yes, cash offers typically close in 7–14 days, while financed deals often take 30–45 days due to lender requirements and appraisals. - Should I accept a lower cash offer if my home is in top condition?
If your home is turnkey and attracts strong financed buyers with waived contingencies, you might net more by accepting a financed offer. Compare risks and your timeline. - How common are cash buyers in Forest Hills?
In the $400K–$1.5M range, cash buyers are less common than financed buyers but are increasing, especially for homes on larger lots or in need of updates. - Can a financed offer be made “as strong as cash”?
Some financed buyers include appraisal gap coverage, waive inspections, or show large down payments, making their offers nearly as reliable as cash—review each term carefully.
Related Forest Hills Seller Resources
- How Do I Handle Possession and Moving Out When Selling My Grand Rapids Home?
- What Should I Know About Pricing My Older East Grand Rapids Home?
- Coordinating Your Grand Rapids Home Sale and New Purchase
About the Author
Jason Pohlonski
is a Michigan licensed real estate salesperson with Keller Williams Grand Rapids East. He helps buyers and sellers throughout East Grand Rapids, Grand Rapids, Forest Hills, Ada, Byron Center, Jenison, Cascade, and surrounding West Michigan communities.
Jason began his real estate career in Chicago in 2004, later expanding his experience in Ann Arbor from 2014 to 2019, and has been serving clients in the Grand Rapids area since 2019.
With over 20 years of combined real estate experience across multiple markets, Jason focuses on helping clients make clear real estate decisions involving pricing, offer terms, inspections, appraisals, relocation timing, and buy-sell planning.
Industry Recognition
Jason is recognized by platforms and industry organizations including Zillow, Grand Rapids Magazine Real Estate All-Stars, and Real Producers for his work serving West Michigan buyers and sellers.
Jason also supports One More Moment, a nonprofit that grants wishes to late-stage cancer patients, by donating $100 for every successful closing.
Professional Disclosure
Jason Pohlonski
Michigan Licensed Real Estate Salesperson
License Verification: Verify Michigan License #6501386166
Brokerage: Keller Williams Grand Rapids East
Brokerage Office: 1555 Arboretum Dr. SE
Grand Rapids, MI 49546
📱 Call or text: 616-916-9770
📅 Schedule consultation:
https://calendly.com/pohlonskirealestate/30min
📧 Email: jpohlonski@kw.com
This article reflects real client experiences and market conditions in East Grand Rapids, Grand Rapids, and surrounding West Michigan communities at the time of publication. Real estate outcomes can vary depending on market conditions, property characteristics, buyer demand, financing terms, inspection results, appraisal results, and lender requirements.
This article is for general informational purposes only and is not legal, tax, financial, insurance, engineering, inspection, or appraisal advice. Buyers and sellers should consult qualified professionals before making decisions involving financing, insurance, inspections, taxes, legal issues, property risk, or valuation.