What should I know about flood risk in Grand Rapids?
If you’re considering buying a home in Grand Rapids, flood risk is something you should check before you make an offer. While most neighborhoods in Grand Rapids aren’t in high-risk flood zones, there are specific areas—especially near the Grand River, Plaster Creek, and low-lying spots—where flood insurance, extra inspection steps, or special financing rules can affect your purchase. Understanding what’s actually involved can save you money, stress, and surprises at closing.
Quick Answer
Most Grand Rapids homes are not in federally designated high-risk flood zones, but certain neighborhoods and properties—especially near the Grand River—may require flood insurance and extra diligence. It’s crucial to check the FEMA flood map, ask your agent about local flood history, and factor in insurance costs early in your decision process.
If you find a home in a mapped floodplain, your lender may require flood insurance, which can impact your monthly payment and closing timeline. If you’re dealing with this situation, I’m happy to walk through it with you.
1. How to Check Flood Zones and Risk Before You Offer
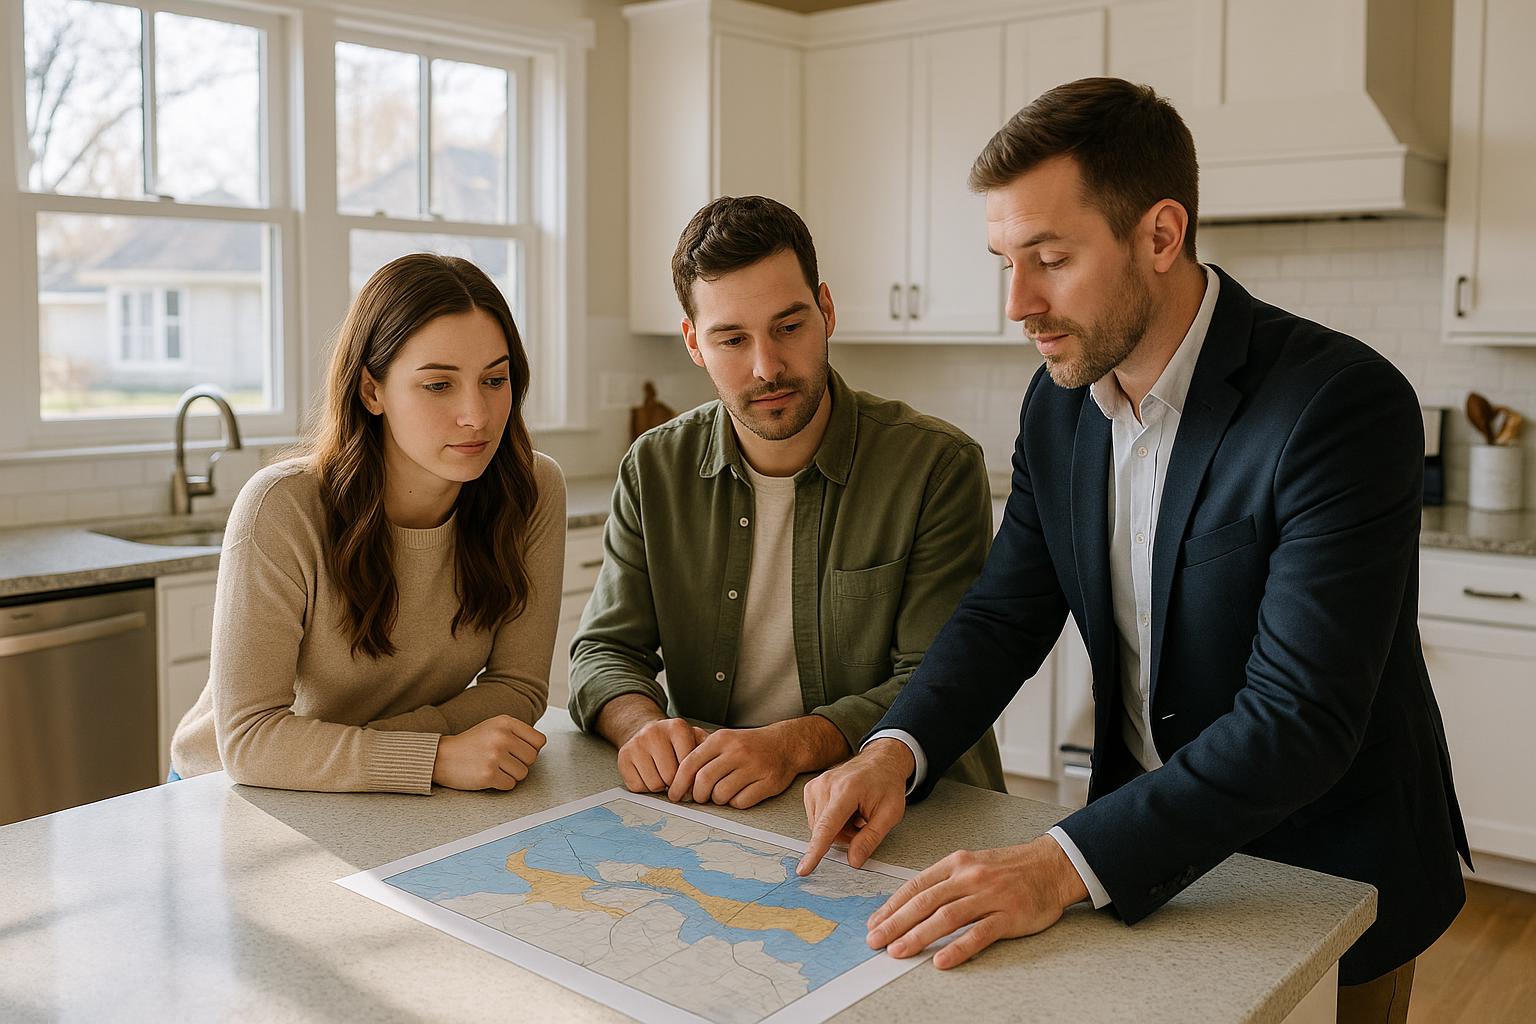
The first step is to check whether the home falls within a FEMA-designated flood zone. You can do this by entering the address on the FEMA Flood Map Service Center. In Grand Rapids, most properties are in “Zone X” (minimal risk), but some, especially along the Grand River, Plaster Creek, or lower-lying areas like parts of Creston, Garfield Park, and Roosevelt Park, may show up in higher-risk “Zone AE” or “Zone A.” If a property is in a Special Flood Hazard Area (SFHA), your lender will require flood insurance.
Jason’s take: I always run a flood zone check for clients before we make an offer—especially on homes near the river, creeks, or with visible sump pumps. It’s quick, and it can save headaches down the road.
2. Understanding Flood Insurance and Its Impact on Your Purchase
If the property is in a high-risk zone, you’ll need a separate flood insurance policy—standard homeowners insurance does not cover flood damage. Flood insurance costs in Grand Rapids can vary widely depending on elevation, foundation type, and the property’s flood history, but expect to pay anywhere from $500 to $2,500+ per year. You can estimate costs using the National Flood Insurance Program’s calculator. Be aware that insurance premiums can impact your loan approval and monthly payment.
In my experience, buyers sometimes overlook the cost of flood insurance until late in the process. It’s best to get a quote as soon as you’re serious about a property, since it can affect your debt-to-income ratio and even your lender’s willingness to close on time.
3. Local Flood History, Disclosures, and Inspection Tips
Even if a home isn’t in a mapped flood zone, localized flooding can still happen—especially in older Grand Rapids neighborhoods with historic basements or near stormwater bottlenecks. Michigan sellers are required to disclose known water issues, but not every seller knows the full history or reports minor past events. That’s why it’s smart to ask neighbors, check city records, and ask your inspector to look for signs of past water entry, sump pumps, or high water tables.
Jason’s take: I recommend buyers budget for a thorough basement inspection and, if you’re in an older neighborhood, ask for a sewer scope or water table check. Even homes outside the floodplain can have water issues due to grading or drainage.
4. Decision Rules and Offer Strategies for Grand Rapids Buyers
If you’re considering two similar homes and one is in a flood zone, here’s a practical rule of thumb: estimate the annual flood insurance cost, add it to your monthly payment, and decide if the neighborhood, school district, or property features outweigh that added expense. For many Grand Rapids buyers, the peace of mind from being outside a high-risk area is worth a slightly higher purchase price elsewhere.
If you’re competing in a multiple-offer scenario, flood zone status can sometimes thin the competition—some buyers walk away when they see the insurance requirement. If you’re comfortable with the risk and cost, you may be able to negotiate better terms or get seller concessions for insurance or mitigation improvements.
Real Buyer Case Study
Last year, I worked with a young couple buying a home in the $325,000–$350,000 range in the Creston neighborhood. The house they loved backed up to a small creek and was partially in Zone AE. We pulled the FEMA map early, confirmed with the lender that flood insurance would be required, and got a quote for $1,350/year. They decided to proceed and used that quote to negotiate a seller credit for their first year’s premium. Their offer was accepted over two others who hesitated over flood concerns. We also had the inspector check for past water entry—no issues found—and the couple has had no problems since.
Grand Rapids Buyer Market Insight
In the current Grand Rapids market, buyers are moving quickly in popular areas, but homes in designated flood zones often sit longer or see fewer offers. I’ve noticed buyers in price ranges under $400,000 are especially cautious about extra insurance costs, while move-up buyers sometimes accept flood risk in exchange for a river view or unique lot. In multiple-offer situations, a clear understanding of flood risk can be a strategic advantage if you’re prepared and have your insurance quotes ready.
Frequently Asked Questions About Buying in Grand Rapids
How do I find out if a Grand Rapids home is in a flood zone?
Enter the address on the FEMA Flood Map Service Center. Ask your agent for help interpreting the map and checking for local floodplain changes.
Does every Grand Rapids home require flood insurance?
No. Only homes in federally mapped high-risk flood zones (typically “Zone AE” or “Zone A”) require flood insurance if you have a mortgage. Most Grand Rapids homes do not need it.
Can I negotiate with sellers if flood insurance is required?
Yes. You can request a seller credit to cover the first year’s premium or negotiate price if flood risk is a new disclosure. Be ready to show your insurance quote.
Will being in a flood zone hurt my home’s resale value?
It can, especially if insurance costs are high or if future buyers are sensitive to flood risk. However, unique properties or locations may still attract buyers willing to accept the risk.
Related Grand Rapids Buyer Resources
- Should I Be Worried About Basement Moisture in Grand Rapids?
- What Should I Look For in a Grand Rapids Home Inspection?
- How to Choose the Right List Price for Your Forest Hills Home
About the Author
Jason Pohlonski
is a Michigan licensed real estate salesperson with Keller Williams Grand Rapids East. He helps buyers and sellers throughout Grand Rapids, East Grand Rapids, Forest Hills, Ada, Byron Center, Jenison, Cascade, and surrounding West Michigan communities.
Jason began his real estate career in Chicago in 2004, later expanding his experience in Ann Arbor from 2014 to 2019, and has been serving clients in the Grand Rapids area since 2019.
With over 20 years of combined real estate experience across multiple markets, Jason focuses on helping clients make clear real estate decisions involving pricing, offer terms, inspections, appraisals, relocation timing, and buy-sell planning.
Industry Recognition
Jason is recognized by platforms and industry organizations including Zillow, Grand Rapids Magazine Real Estate All-Stars, and Real Producers for his work serving West Michigan buyers and sellers.
Jason also supports One More Moment, a nonprofit that grants wishes to late-stage cancer patients, by donating $100 for every successful closing.
Professional Disclosure
Jason Pohlonski
Michigan Licensed Real Estate Salesperson
License Verification: Verify Michigan License #6501386166
Brokerage: Keller Williams Grand Rapids East
Brokerage Office: 1555 Arboretum Dr. SE, Grand Rapids, MI 49546
📱 Call or text: 616-916-9770
📅 Schedule consultation:
https://calendly.com/pohlonskirealestate/30min
📧 Email: jpohlonski@kw.com
This article reflects real client experiences and market conditions in Grand Rapids and surrounding communities at the time of publication. Real estate outcomes can vary depending on market conditions, property characteristics, buyer demand, financing terms, inspection results, appraisal results, and lender requirements.
This article is for general informational purposes only and is not legal, tax, financial, insurance, engineering, inspection, or floodplain determination advice. Buyers and sellers should consult qualified professionals before making decisions involving financing, insurance, inspections, taxes, legal issues, or property risk.